
In one of the most substantial private capital commitments directed toward the domestic industrial base in recent decades, Re:Build Manufacturing has secured $2.1 billion in a new financing round designed to dramatically scale its physical production footprint and venture creation engine. The colossal funding event, jointly led by venture firm General Catalyst and JPMorganChase’s Strategic Investment Group, signals a profound structural shift in how institutional investors perceive the intersection of advanced manufacturing, national security, and capital-intensive hard technology.
Headquartered in Massachusetts, Re:Build was established with an explicit, contrarian mandate: reverse decades of industrial hollowing-out across the United States by creating an integrated, high-throughput manufacturing infrastructure capable of taking novel physical concepts from digital blueprints into high-volume commercial reality. The newly acquired capital will serve as a liquidity reservoir to fuel the expansion of specialized manufacturing facilities, support strategic acquisitions of industrial capabilities, and incubate nascent technology enterprises operating in underserved industrial niches.
The massive round arrives amid a protracted reassessment of global trade dependencies. Decades of asset-light corporate strategies—characterized by outsourcing tooling, casting, machining, and final assembly to overseas hubs, primarily in mainland China—have left Western supply chains vulnerable to geopolitical friction, export controls, and acute transport disruptions. By positioning itself as a domestic counterweight to sophisticated overseas fabrication ecosystems, Re:Build is testing whether modern digital orchestration, deep capitalization, and advanced engineering can restore cost-effective, domestic mass production.
The Operational Architecture: Marrying Scale with Incubation
Re:Build’s operating model diverges sharply from conventional contract manufacturers and boutique industrial design agencies. Rather than operating purely as a job shop executing discrete orders, the organization functions as a hybrid industrial conglomerate and venture foundry. Its core activities are divided into two interdependent operational vectors.
On one side, the enterprise partners with established industrial, defense, and aerospace corporations to co-design, re-engineer, and scale complex mechanical and electromechanical assemblies. Across sectors where precision tolerances, regulatory compliance, and supply assurance are paramount, Re:Build provides end-to-end manufacturing workflows. This includes everything from initial prototyping and structural engineering to tooling fabrication, automated assembly, and systemic quality assurance.
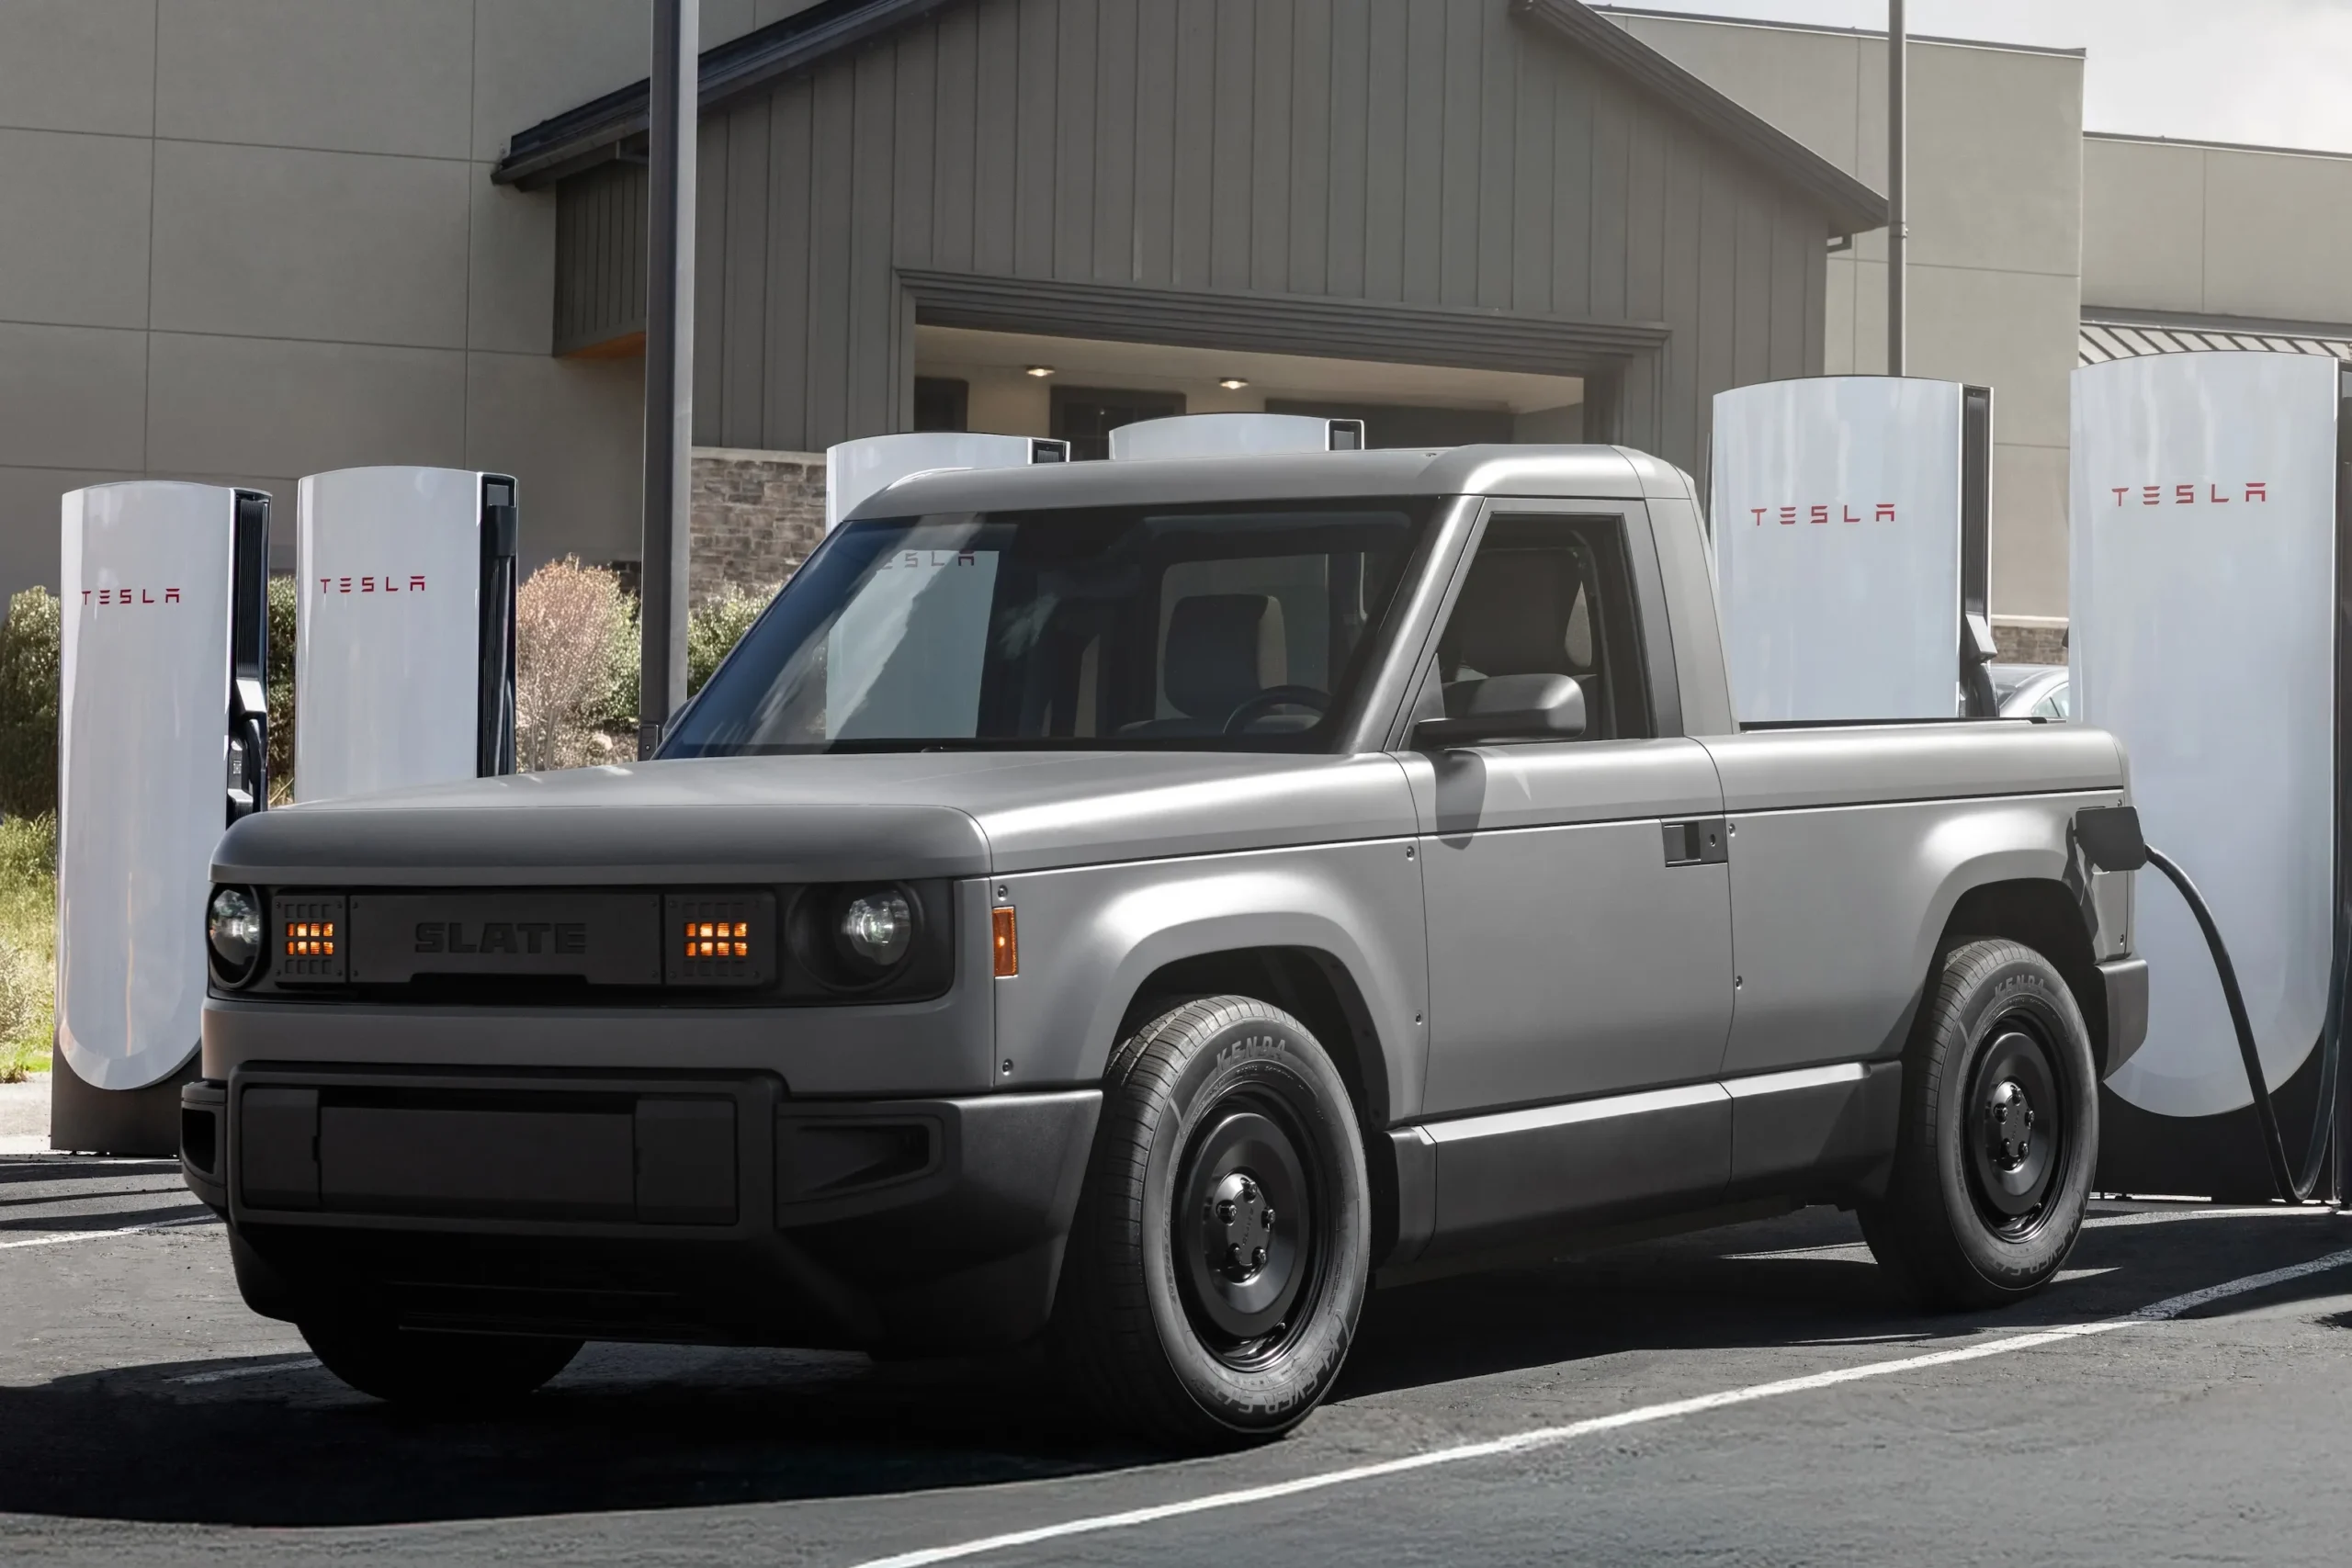
On the other side lies Re:Build’s internal incubation engine, which identifies strategic market voids in critical sectors and constructs autonomous enterprises to exploit them. The preeminent illustration of this thesis is Slate Auto. Conceived in 2022 by Re:Build co-founders Jeff Wilke and Miles Arnone, Slate Auto was established to tackle the escalating cost and mechanical complexity of the modern commercial vehicle market.
Recognizing that the capital requirements and risk profile of an automotive original equipment manufacturer (OEM) would distort Re:Build’s broader operations, leadership spun out Slate Auto into an independent operating entity in 2023. The startup has since raised more than $1.4 billion in external capital, including substantial backing from Jeff Bezos’ family office, Bezos Expeditions. Slate Auto’s industrial objective centers on producing a utility-first, modular, ultra-low-cost electric pickup truck, stripped of non-essential consumer software luxuries and engineered for maximum durability, ease of maintenance, and commercial fleet utility.
The relationship between Re:Build and Slate Auto provides an operational blueprint for the company’s venture studio: identifying capital-intensive, hardware-dependent sectors that incumbent consumer venture funds often bypass, designing the underlying physical product within Re:Build’s manufacturing umbrella, and then capitalizing the vehicle through targeted private placements once the engineering feasibility is established.
The Amazon Pedigree and Algorithmic Manufacturing
A defining characteristic of Re:Build is its executive leadership, which possesses deep ties to the modern era of hyper-scale logistics, automated fulfillment, and algorithmic supply chain design.
Co-founder and Chairman Jeff Wilke spent more than two decades at Amazon, ultimately serving as the Chief Executive Officer of its Worldwide Consumer business before retiring from the e-commerce giant in early 2021. Wilke, who held an advanced engineering degree and played a foundational role in constructing Amazon’s proprietary fulfillment network and operations culture, brought with him a cohort of high-ranking technical and operational veterans.
Among them is Wei Gao, who serves as Re:Build’s Chief Digital and Product Officer. Gao spent over 15 years at Amazon, ascending to vice president roles across enterprise supply chains and serving as a technical advisor to Jeff Bezos. The broader executive bench is similarly populated by former operational leads, systems architects, and industrial automation engineers drawn from large-scale technology and aerospace enterprises.
This operational lineage informs Re:Build’s underlying thesis. While traditional American manufacturing has often suffered from fragmented family-owned tooling shops, legacy enterprise resource planning (ERP) platforms, and brittle regional supplier links, Re:Build applies modern data pipelines, distributed production modeling, and robotic automation to legacy production challenges.
The aspiration is often framed internally as building “America’s answer to Shenzhen.” Over the past forty years, the Shenzhen manufacturing cluster in China’s Pearl River Delta evolved into the global epicenter of hard-tech commercialization precisely because of its rapid iteration cycles. In Shenzhen, an engineer can draft a circuit board or mechanical housing in the morning, have raw components cast or printed by afternoon, and test integrated production runs within days due to the extreme geographic density of sub-tier suppliers.
Re:Build aims to replicate that cross-disciplinary velocity within the United States, not necessarily through geographical concentration in a single metropolitan zone, but through a unified operational and digital fabric spanning dozens of regional facilities. As of this funding round, Re:Build oversees an industrial network comprising more than 2,100 personnel across more than 2.4 million square feet of operational manufacturing floor space.
The Macroeconomic Imperative: De-Risking the Supply Base
The timing of this $2.1 billion liquidity infusion coincides with an aggressive realignment of American economic and defense policy. For nearly three decades, industrial outsourcing was viewed through the lens of pure cost optimization, with global supply networks optimized for just-in-time delivery and lowest-unit labor costs.
However, the cascading systemic shocks of the early 2020s—compounded by intensifying trade barriers, cross-strait geopolitical tensions surrounding semiconductor and hard-tech supply chains, and industrial capacity shortfalls exposed by international conflicts—have elevated manufacturing resilience to a paramount matter of statecraft.
Federal interventions, including the CHIPS and Science Act and targeted domestic content provisions embedded within broad energy legislation, have created institutional incentives for reshoring. Yet, significant structural bottlenecks persist. While capital has flowed into mega-projects such as semiconductor front-end fabrication facilities and primary battery cell gigafactories, the critical intermediary tiers of the industrial ecosystem—the precision machinists, precision injection molders, composite fabricators, and specialized assembly lines—remain severely undercapitalized.
Industry observers frequently identify this dynamic as the "missing middle" of American industry. If an aerospace contractor or advanced robotics startup requires high-tolerance titanium components, complex wiring harnesses, or hermetically sealed sensor enclosures, it routinely encounters multi-month domestic lead times or is forced to rely on overseas vendors.
General Catalyst, an early backer of defense and critical infrastructure platforms through its "Global Resilience" investment thesis, views this missing middle as an addressable market. Hemant Taneja, CEO of General Catalyst, has consistently argued that maintaining technological leadership requires parity in physical production. Software-defined platforms cannot achieve real-world utility without robust, reliable, and rapidly reconfigurable manufacturing capacity. By backing Re:Build with multi-billion-dollar scale alongside institutional partners like JPMorganChase, private markets are signaling that industrial physical plants are once again being viewed as strategically defensible, yield-generating infrastructure assets.
Overcoming Structural Friction in Domestic Production
Despite the vast scale of the capital raise, Re:Build faces substantial headwinds inherent to the physical fabrication landscape. Modernizing domestic industrial operations requires navigating structural deficits that capital alone cannot instantly remediate.
Chief among these challenges is the acute shortage of skilled domestic labor. Decades of cultural and educational emphasis on digital, service, and software-focused occupations have led to a critical contraction in the domestic workforce of CNC machinists, tool-and-die makers, certified welders, and industrial automation technicians. The retirement of seasoned trade craftspeople has outpaced the inflow of new vocational talent. To achieve sustainable cost parity and scale, Re:Build must continuously invest in advanced industrial robotics, autonomous materials handling, and computer-vision-assisted quality inspection to offset higher labor overhead and headcount constraints.
Furthermore, capital intensity remains a defining reality of heavy industry. Unlike enterprise software operations that enjoy gross margins exceeding 80% and minimal marginal costs per new user, industrial operations require continuous capital expenditure: computer numerical control (CNC) five-axis mills, additive manufacturing equipment, cleanrooms, environmental testing chambers, and raw materials procurement. Managing depreciation cycles, plant utilization rates, and operational overhead during macroeconomic downturns requires rigorous balance-sheet management and constant throughput.
The company must also demonstrate that its integrated model can remain price-competitive for commercial customers who are sensitive to unit economics. While aerospace and defense clients are often willing to pay a premium for localized, ITAR-compliant, secure production runs, purely commercial sectors—such as consumer robotics, commercial fleets, and clean energy hardware—face relentless margin pressure. Re:Build’s long-term success will hinge on whether its operational efficiencies and engineering integration can compress lead times and non-recurring engineering (NRE) costs sufficiently to offset foreign wage and supply differentials.
The Broader Trajectory of Hardware Renaissance
The scale of Re:Build’s capitalization indicates a broader paradigm shift across private equity and venture capital. The historic bias toward asset-light, purely digital businesses is increasingly balancing out against the realization that physical infrastructure underpins sovereign technological independence.
From autonomous systems and hypersonic flight profiles to high-density grid infrastructure and localized electric vehicle manufacturing, the defining technological battles of the next quarter-century will be waged at the intersection of bits and atoms. Advanced software requires bespoke silicon, high-bandwidth compute demands robust thermodynamic dissipation hardware, and transformative mobility models require cost-efficient, physical platforms built to institutional tolerances.
As Re:Build deploys this $2.1 billion capital tranche, its strategic roadmap will likely focus on three primary avenues: aggressive inorganic growth through the acquisition of specialized, niche manufacturing suppliers that possess rare capabilities but lack digital systems; substantial investments in state-of-the-art regional manufacturing hubs equipped with flexible automation; and the expansion of its startup studio to engineer new, sovereign hardware enterprises following the operational trail blazed by Slate Auto.
The experiment underway at Re:Build is ultimately a test case for the viability of modernized industrial capitalism. If the organization can successfully combine Amazonian logistical rigor with the flexible, rapid prototyping capabilities of advanced global foundries, it may establish a reproducible blueprint for revitalizing domestic manufacturing capacity—transforming the Rust Belt’s legacy capabilities into a resilient engine for the next generation of hard-tech innovation.
